
Updated for tax year 2026.
Adjusted gross income (AGI) is your total taxable income minus certain adjustments to income. AGI is an important number on your federal tax return because it can affect your taxable income and eligibility for certain tax deductions and credits.
Let’s take a deep dive into how AGI is calculated and why it matters.
At a glance:
- AGI is your gross income minus specific adjustments, which the IRS uses as a starting point to determine your taxable income.
- Calculate your AGI by subtracting adjustments from your gross income.
- Your AGI can determine your eligibility for certain tax breaks.
What is adjusted gross income (AGI)?
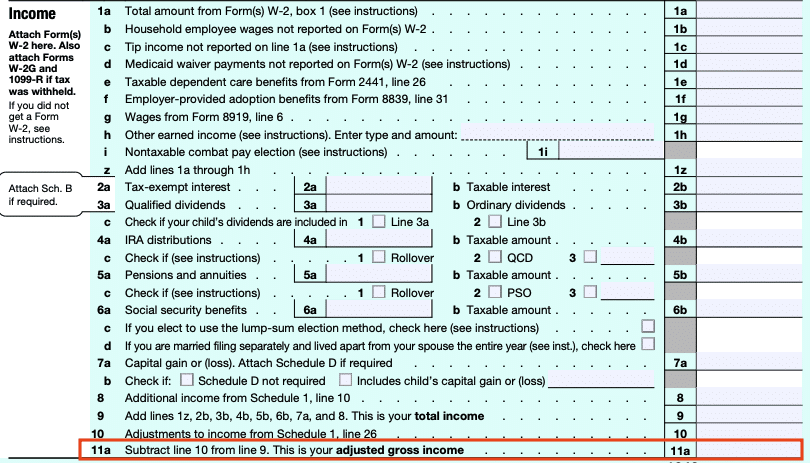
Essentially, your AGI is your gross income minus any adjustments. The Internal Revenue Service (IRS) uses your AGI to determine how much tax you owe, and it can influence which tax deductions and credits you can take. It’s noted on IRS Form 1040:
AGI vs. MAGI vs. taxable income
In addition to AGI, you may also see the terms “MAGI” and “taxable income” when filing your taxes. These terms are related, but they are not the same:
| Term | What it means |
|---|---|
| Adjusted gross income (AGI) | Your income after certain adjustments to income are subtracted. |
| Modified adjusted gross income (MAGI) | Your AGI with certain deductions added back or otherwise adjusted. This is often used to determine eligibility for certain tax benefits, but the exact calculation can vary. |
| Taxable income | The final amount of income left after all deductions are taken into account (the amount you actually pay taxes on). |
Understanding gross income
To understand AGI, we first need to define gross income. Gross income is the total income you earn in a year before any taxes or other deductions are taken out.
Common types of gross income
- Wages and salaries: Earnings from your job, plus any bonuses or tips.
- Interest and dividends: Money earned from investments like savings accounts, bonds, and stocks.
- Capital gains: Profits from selling capital assets like stocks, bonds, or real estate.
- Business income: Net business or self-employment income after allowable business expenses.
- Rental property income: Net rental income after allowable rental expenses.
- Unemployment benefits: Payments received as unemployment compensation.
- Social Security: Any Social Security distributions you received.
Other types of gross income
- Alimony received: Payments received from a former spouse (only for divorces finalized before 2019).
- Royalties: Income from intellectual property such as patents, trademarks, or books.
- Gambling winnings: Any money you win from gambling activities, including lotteries, casinos, and betting pools.
Adjustments to income
You must make certain adjustments to your gross annual income to calculate your adjusted gross income. Makes sense, right? These adjustments are specific expenses that the IRS allows you to subtract from your gross income. They are also sometimes called above-the-line deductions — “the line” refers to your calculated AGI on your federal income tax return (Form 1040).
The deductions you can make depend on your personal tax situation. We will highlight some common income adjustments below, but don’t worry too much about them. If you use TaxAct®’s DIY tax preparation software, we will ask you detailed questions to determine what specific deductions you qualify for and guide you through the tax filing process.
Common adjustments to income for tax year 2026
- Educator expenses: Eligible educators can deduct up to $350 of qualifying unreimbursed expenses for tax year 2026.
- Student loan interest: Eligible students may deduct up to $2,500 of interest paid on student loans.
- IRA contributions: Contributions to a traditional IRA may be deductible depending on your income.
- Health savings account (HSA) contributions: If you have a high-deductible health plan, contributions to an HSA are deductible.
Other adjustments to income
- Self-employment tax: Self-employed individuals can deduct half of their self-employment tax.
- Self-employed health insurance: If you’re self-employed, you can deduct the cost of your health insurance premiums.
- Moving expenses for military: Certain active-duty Armed Forces members and qualifying members of the intelligence community may deduct eligible moving expenses.
- Penalty on early withdrawal of savings: If you withdrew money early from a CD or another time-deposit savings account, you might be able to deduct the penalty.
- Certain business expenses: Some professionals can deduct specific work-related expenses.
- Contributions to SEP, SIMPLE, and qualified plans: Self-employed individuals can deduct contributions to certain retirement accounts.
- Alimony paid: For divorces finalized before 2019, alimony payments are deductible.
Other deductions that can lower taxable income (but not AGI)
We already know AGI is your income after adjustments, but your taxable income is calculated later, after additional deductions are applied. That means some deductions can lower your taxable income without lowering your AGI.
For example, most adjustments that reduce AGI are reported on Schedule 1. However, some newer deductions, like those introduced by the Working Families Tax Cuts (a.k.a. One Big Beautiful Bill), are reported separately on Schedule 1-A. These new deductions reduce taxable income rather than AGI:
- Qualified tips: Eligible workers may be able to deduct qualified tip income.
- Qualified overtime: Eligible workers may be able to deduct qualified overtime compensation.
- Car loan interest: Eligible taxpayers may be able to deduct interest paid on certain qualifying vehicle loans.
- Enhanced deduction for seniors: Eligible taxpayers age 65 or older may qualify for an additional deduction.
How to calculate adjusted gross income explained
Calculating your AGI is straightforward if you follow these steps:
- Start with your gross income: This includes all your earnings from wages, investments, and other sources discussed above.
- Subtract adjustments to income from Schedule 1: Deduct the allowed adjustments, such as educator expenses, student loan interest, and HSA or IRA contributions.
Need help? Try out TaxAct’s easy-to-use AGI calculator.
Example AGI calculation
Let’s review a more detailed example to illustrate how to calculate AGI with multiple types of income and adjustments.
Imagine your total gross income for the year as a single taxpayer includes:
- Wages: $50,000
- Rental income: $10,000
- Dividends: $2,000
- Business income: $8,000
- Gambling winnings: $500
Adding all those together, your total gross income would be $70,500.
Next, let’s say you had the following adjustments:
- Student loan interest: $2,000
- IRA contributions: $3,000
- Health savings account contributions: $1,000
- Self-employment tax deduction: $565 (half of $1,130)
- Self-employed health insurance: $2,500
Adding those together, your total adjustments would be $9,065.
Finally, subtract your adjustments from your gross income to find your AGI: $70,500 (gross income) – $9,065 (adjustments) = $61,435 AGI.
FAQs about AGI
The bottom line
Understanding your AGI is essential for tax planning purposes. By taking advantage of tax benefits and adjustments, you can potentially lower your taxable income and overall tax bill. And don’t forget, TaxAct can help you claim valuable tax deductions and simplify tax filing when you use our DIY tax prep software.
For more in-depth reading, you can visit the IRS website on AGI.
This article is for informational purposes only and not legal or financial advice.
All TaxAct offers, products and services are subject to applicable terms and conditions.
The One Big Beautiful Bill (OBBB) is now also being referred to by lawmakers as the Working Families Tax Cut Act. You may see one or both names used here, but they refer to the same set of tax changes.
Citations
Internal Revenue Service. “Adjusted Gross Income.” IRS.gov, 28 June 2026.
Ponder, Meghen. “What Is Form W-2, and How Does It Work?.” TaxAct Blog, 10 October 2024.
Ponder, Meghen. “How Your Year-End Bonus Is Taxed.” TaxAct Blog, 22 November 2025.
Ponder, Meghen. “Taxes on Investments: What Investors Need to Know.” TaxAct Blog, 16 January 2026.
Ponder, Meghen. “How Capital Gains Tax Works: Short-Term vs. Long-Term Gains.” TaxAct Blog, 9 April 2026.
TaxAct. “Schedule C: Reporting Self-Employment Income from Multiple Sources.” TaxAct Blog, 16 January 2026.
Ponder, Meghen. “Tax Implications of Owning Rental Property.” TaxAct Blog, 4 November 2025.
Ponder, Meghen. “Is Unemployment Compensation Taxable Income?.” TaxAct Blog, 4 May 2026.
Ponder, Meghen. “Guide to Social Security Taxes.” TaxAct Blog, 21 May 2026.
Ponder, Meghen. “How to File Taxes After Divorce or Separation.” TaxAct Blog, 1 July 2025.
TaxAct. “Writing Off Gambling Losses on Your 2024 Taxes.” TaxAct Blog, 15 October 2024.